来源:本文由计量经济学服务中心综合整理自:Generalized method of moments estimation of linear dynamic panel data models,作者:
Sebastian Kripfganz,University of Exeter Business School, Department of Economics, Exeter, UK
转载请注明出处
前言:
xtdpdgmm实现了线性动态面板数据模型的广义矩法(GMM)估计。除了Arellano and Bond (1991), Arellano and Bover (1995), and Blundell and Bond (1998)可以实现线性矩条件的GMM估计,xtdpdgmm也可以合并Ahn and Schmidt(1995)提出的非线性矩条件。后者对于高持久性数据,可以产生更好的以及稳健结果。
1
动态面板数据命令回顾
December 15, 2000: Stata 7 released with the new xtabond
command for the Arellano and Bond (1991) difference GMM
(diff-GMM) estimation.
November 26, 2003: David Roodman announced the
community-contributed xtabond2command for Arellano and
Bover (1995) and Blundell and Bond (1998) system GMM
(sys-GMM) estimation.
June 25, 2007: Stata 10 released with the new xtdpdsys
command for sys-GMM estimation. Both xtabond and
xtdpdsys are wrappers for the xtdpd command.
March 2009: David Roodman’s “How to do xtabond2” article
appeared in the Stata Journal.
July 13, 2009: Stata 11 released with the new gmm command
for GMM estimation (not just of dynamic panel data models).
December 2012: Stata Journal Editor’s Prize for David
Roodman.
June 1, 2017: New community-contributed xtdpdgmm
command for sys-GMM estimation and GMM estimation with
the Ahn and Schmidt (1995) nonlinear moment conditions
announced on Statalist.
2
Generalized method of moments estimation of linear dynamic panel data models
命令为xtdpdgmm,下载安装方法为:
命令语法格式为:
iv(iv_spec):可以指定工具变量。您可以根据需要指定任意多个工具变量。允许的子选项是差分或者水平。
gmmiv(gmmiv_spec):指定GMM-type instruments
noserial:假设连续不相关的特质性误差
wmatrix(wmat_spec):指定用于获得一阶GMM估计或两步GMM估计的初始估计的加权矩阵。 可以是unadjusted, independent, or separate种的选项。
vce(vcetype):稳健标准误估计,选项可以实conventional or robust
level(#):设置置信水平,默认为 level(95)
coeflegend:display legend instead of statistics
noheader:suppress output header
notable:suppress coefficient table
display_options: control columns and column formats, row spacing, line width, display of omitted variables and base and empty cells, and factor-variable labeling
3
动态面板操作命令
Equivalent diff-GMM implementations in Stata1
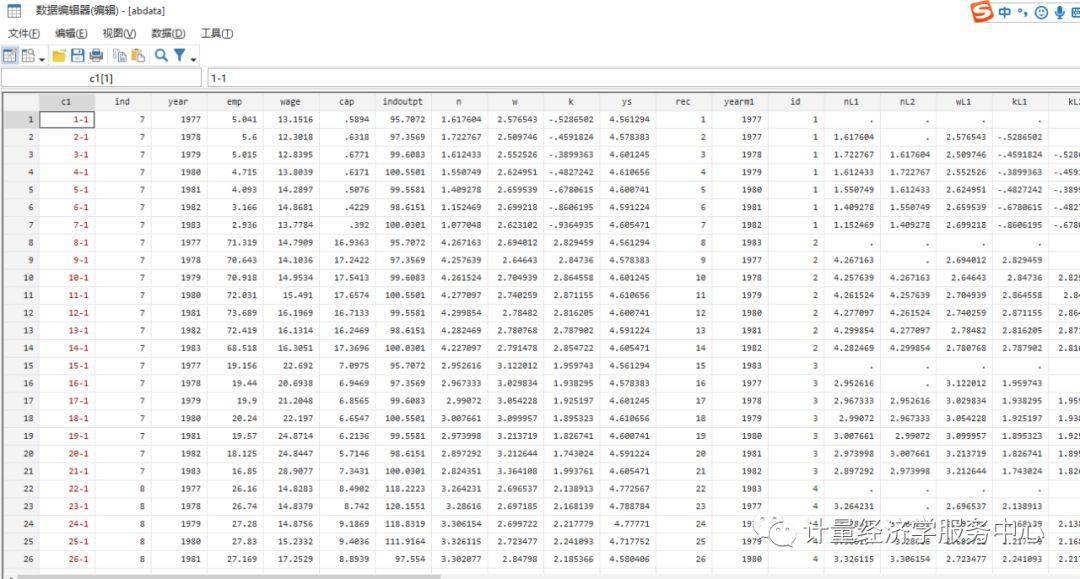
1、导入数据
查看数据,结果为:
2、操作命令
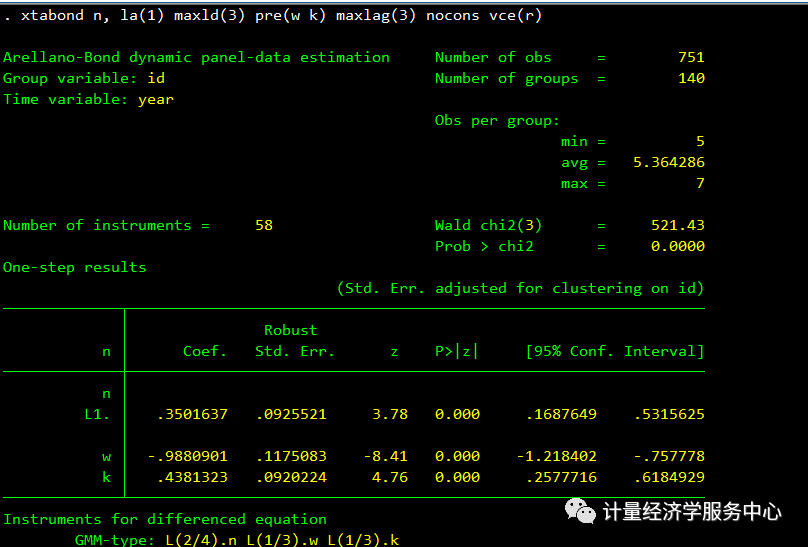
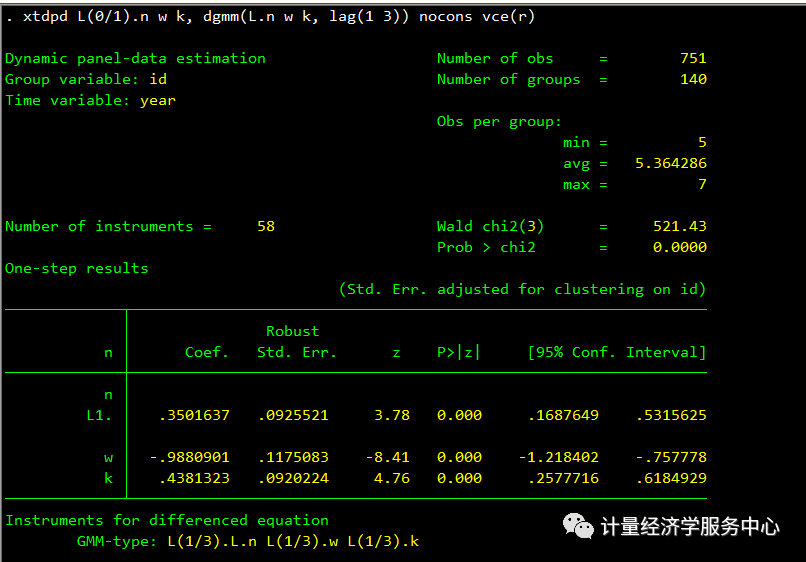
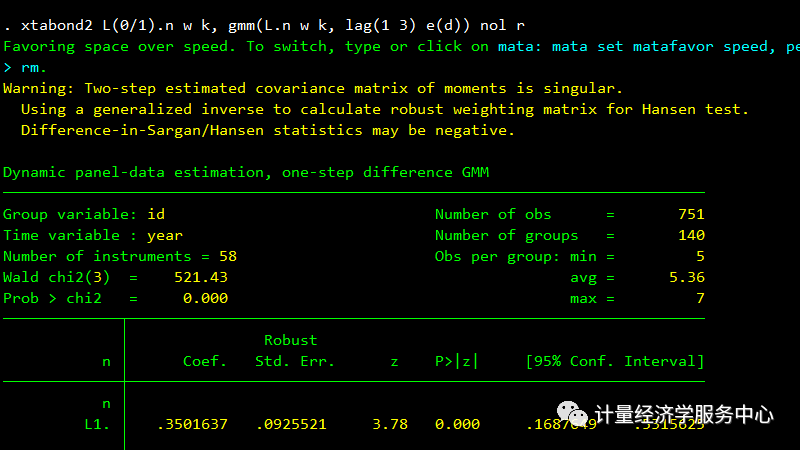
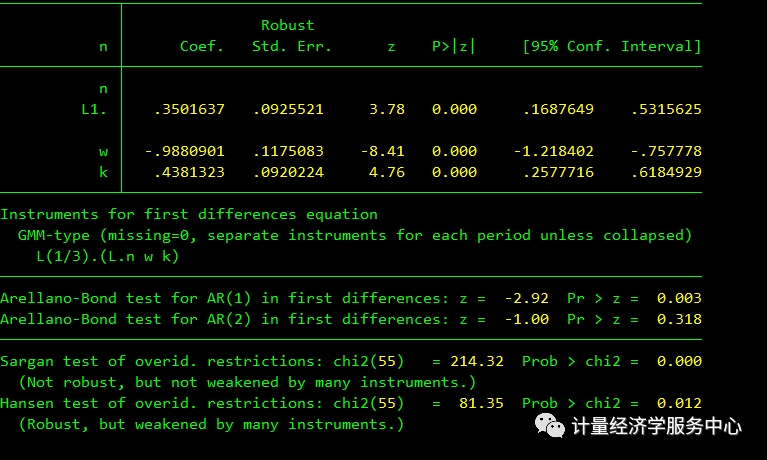
xtabond n, la(1) maxld(3) pre(w k) maxlag(3) nocons vce(r)xtdpd L(0/1).n w k, dgmm(L.n w k, lag(1 3)) nocons vce(r)xtabond2 L(0/1).n w k, gmm(L.n w k, lag(1 3) e(d)) nol r
xtdpdgmm L(0/1).n w k, gmm(L.n w k, l(1 3) m(d)) nocons vce(r)
gmm (D.n - {b1} *LD.n - {b2}*D.w - {b3}*D.k), /// > xtinst(L.n w k, lags(1/3)) inst(, nocons) winit(xt D) one vce(r)
3、操作命令
gmm (D.n - {b1} *LD.n - {b2}*D.w - {b3}*D.k) /// > (n - {b1}*L.n - {b2}*w - {b3}*k - {c}), ///> xtinst(1: L.n w k, lags(1/3)) inst(1:, nocons) ///> xtinst(2: D.(L.n w k), lags(0)) winit(xt DL) wmat(r) vce(un) nocommonesample
4
动态面板模型之 GMM 估计(xtdpdgmm)
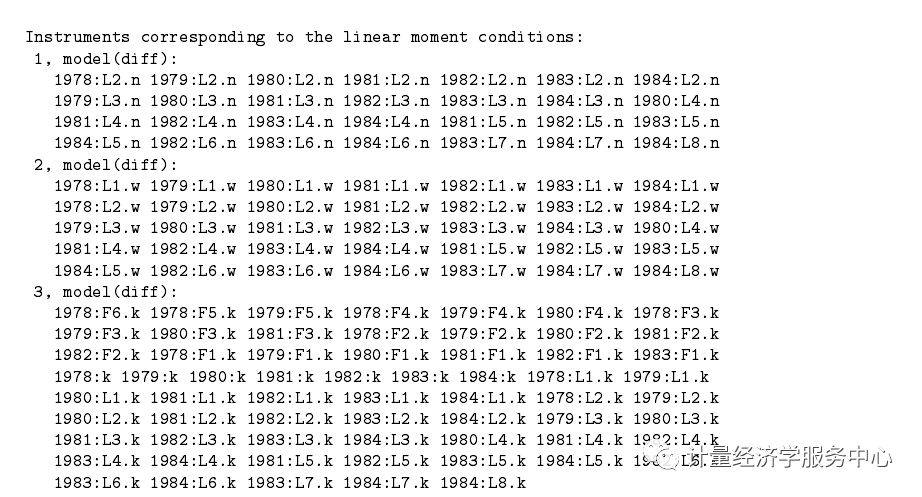
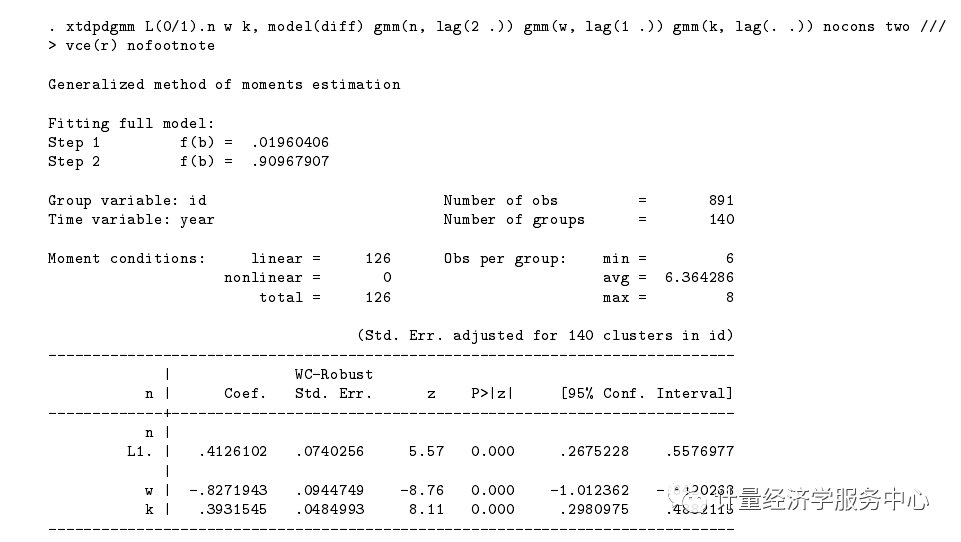
1、 一阶差分GMM估计
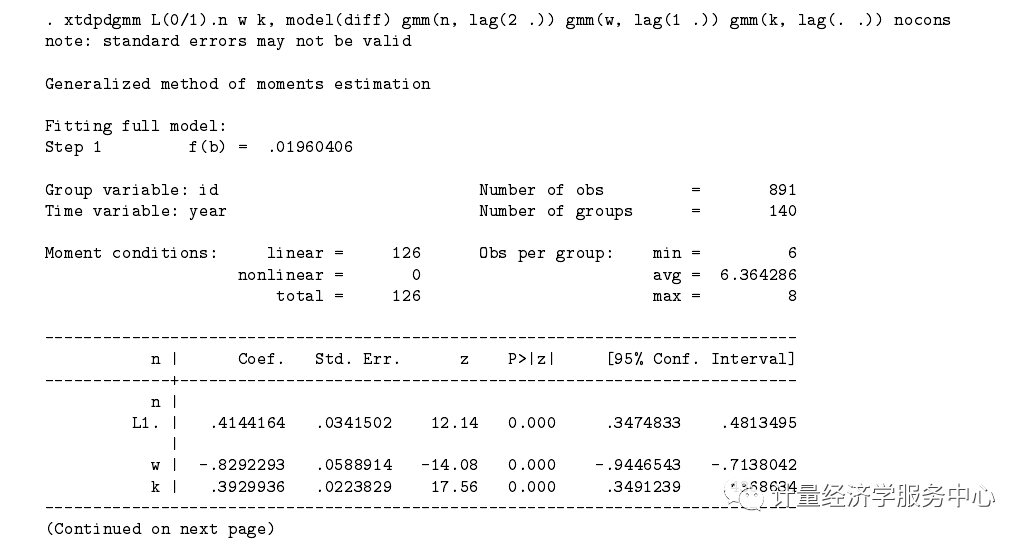
注意:xtdpdgmm有选项nolog,noheader,notable,nofootnote不输出结果
2、Two-step diff-GMM estimation in Stata
3、序列相关检验
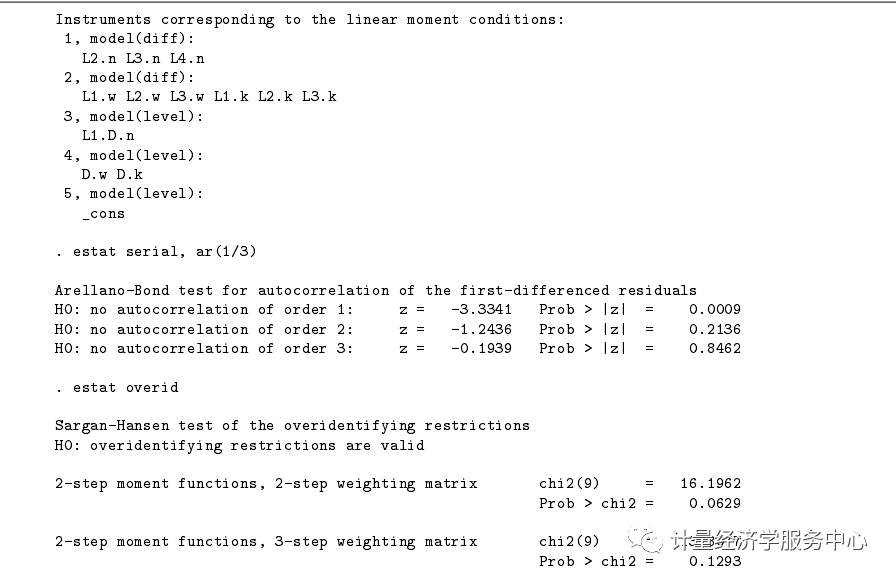
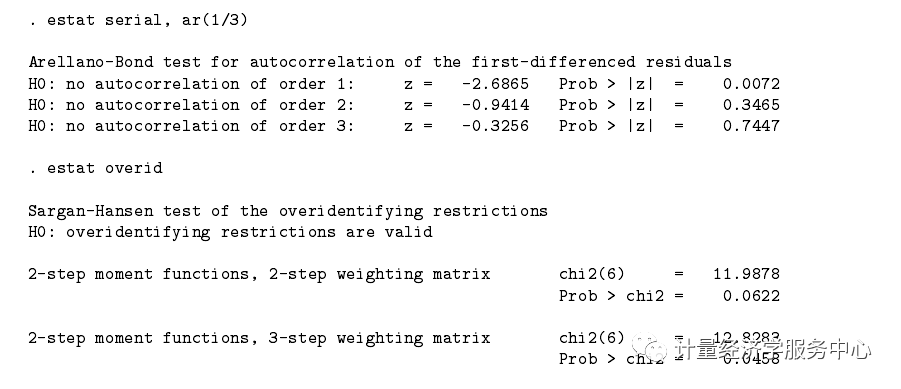
使用xtdpdgmm之后,序列相关检验是用postestimation命令estat serial来进行检验的
Sargan’s overidentification tests
相关检验命令介绍应用
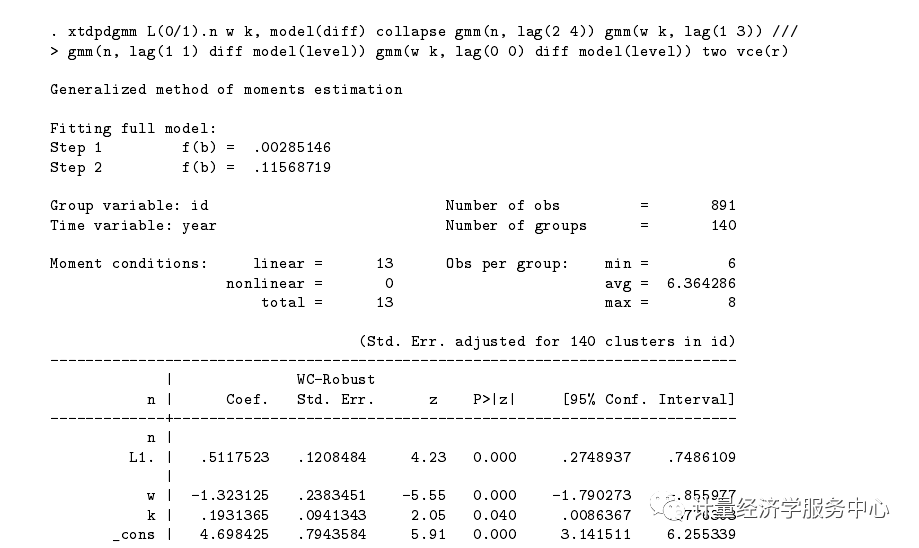
4、系统GMM估计