摘要
High-dimensional time series data appear in many scientific areas in the current data-rich environment. Analysis of such data poses new challenges to data analysts because of not only the complicated dynamic dependence between the series, but also the existence of aberrant observations, such as missing values, contaminated observations, and heavy-tailed distributions. For high-dimensional vector autoregressive (VAR) models, we introduce a unified estimation procedure that is robust to model misspecification, heavy- tailed noise contamination, and conditional heteroscedasticity. The proposed methodology enjoys both statistical optimality and computational efficiency, and can handle many popular high-dimensional models, such as sparse, reduced-rank, banded, and network-structured VAR models. With proper regularization and data truncation, the estimation convergence rates are shown to be almost optimal in the minimax sense under a bounded (2 + 2ε)-th moment condition. When ε ≥ 1, the rates of convergence match those obtained under the sub-Gaussian assumption. Consistency of the proposed estimators is also established for some ε ∈ (0, 1), with minimax optimal convergence rates associated with ε. The efficacy of the proposed estimation methods is demonstrated by simulation and a U.S. macroeconomic example. This talk is based on the joint work with Ruey S. Tsay.
嘉宾介绍
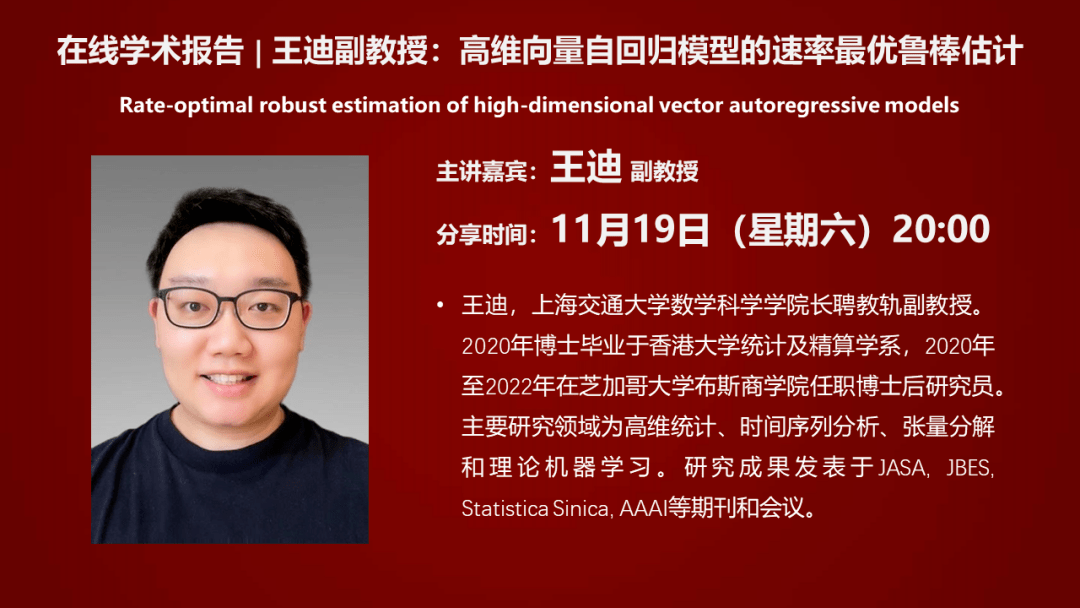
王迪,上海交通大学数学科学学院长聘教轨副教授。2020年博士毕业于香港大学统计及精算学系,2020年至2022年在芝加哥大学布斯商学院任职博士后研究员。主要研究领域为高维统计、时间序列分析、张量分解和理论机器学习。研究成果发表于JASA, JBES, Statistica Sinica, AAAI等期刊和会议。
狗熊会线上学术报告厅向数据科学及相关领域的学者及从业者开放,非常期待各位熊粉报名或推荐报告人。相关事宜,请联系:常莹,ying.chang@clubear.org。
请添加熊二(clubear2)获取参会方式~ 返回搜狐,查看更多